Why the Standard Social Security Calculator Is Lying to You (And What to Do Instead)
If you plugged your numbers into a mainstream Social Security calculator this week, you got a clean, comforting number. A single line. A steady paycheck that arrives every month until you die, growing quietly with inflation, taxed lightly, and guaranteed forever.
That number is fiction.
Every major site; NerdWallet, Investopedia, Smart Asset, Fidelity tells you the same three things: open a mySocialSecurity account, find your Full Retirement Age (FRA), and decide whether to claim at 62, at FRA, or wait until 70. Then they hand you a calculator and wish you luck.
That advice isn't wrong. It's just dangerously incomplete. It ignores the six things that actually determine whether your retirement plan survives contact with reality:
benefit cuts
tax torpedoes
a spouse's death
market crashes while you wait to claim
healthcare inflation
pension offsets that can wipe out your check entirely
This guide covers the basics fast and then goes where nobody else will.
Why the Standard Social Security Calculator Is Lying to You (And What to Do Instead)
Part 1: The Basics (Fast Because You Already Know This)
Part 2: The Six Hidden Dangers Standard Calculators Ignore
1. The "Doomsday" Stress Test - Modeling a Legislative Benefit Cut
2. The Tax Torpedo - How "Up to 85% Taxable" Actually Detonates
3. The Survivor's Cliff - The Income Drop Nobody Models
4. Bridging the Gap - Sequence of Returns Risk While You Wait to Claim
5. The COLA vs. Healthcare Inflation Disconnect
6. The WEP and GPO Blind Spot for Teachers, Firefighters, and Government Employees
Part 3: Putting It All Together - The Complete Projection Worksheet
Get the Free Advanced Tools: Get More From Every Investment Decision
Quick-Answer Summary
To correctly include Social Security in a retirement projection, you must model six variables most calculators ignore:
If your projection doesn't account for all six, it's not a projection; it's a guess with a nice font.
Part 1: The Basics (Fast Because You Already Know This)
Before we get into what actually matters, here's the 90-second version of what every other article spends 2,000 words on:
Full Retirement Age (FRA): Between 66 and 67, depending on your birth year.
Claiming at 62: Locks in a permanently reduced benefit - as much as 30% less than your FRA amount.
Claiming at 70: Maximizes your benefit. Roughly 24-32% more than your FRA amount, growing about 8% per year you delay past FRA.
Your official number: Create an account at ssa.gov/myaccount and pull your actual earnings-based estimate. Never use a generic "average" number! Yours is based on your unique 35-year earnings history.
That's the floor. Everyone stops here. You're about to go somewhere they don't.
Part 2: The Six Hidden Dangers Standard Calculators Ignore
1. The "Doomsday" Stress Test - Modeling a Legislative Benefit Cut
Here's what every article says: "Don't worry, Social Security isn't going bankrupt."
Here's what they don't say: the Social Security trust fund is projected to deplete its reserves somewhere between 2033 and 2035.
If Congress does absolutely nothing between now and then, the historical default setting for Congress, incoming payroll taxes will only cover about 76-80% of scheduled benefits.
That means an automatic, across-the-board cut of roughly 20% to 24% for every single beneficiary, regardless of age or income.
Most people are planning as if this risk doesn't exist. That's not optimism; it's a planning error.
How to build this into your projection:
Take your full projected benefit at your chosen claiming age.
Build two columns in your spreadsheet: "Full Benefit" and "Stress-Tested Benefit."
For every year after 2034, multiply your benefit by 0.80 in the stress-tested column.
Run your entire retirement plan against the stress-tested number, not the optimistic one.
If your plan still works when Social Security pays you 20% less starting in your 70s or 80s, you have a real plan.
If it collapses, you now know exactly how much extra you need to save today to close that gap; which is precisely the kind of urgency a late-start investor needs to hear.
2. The Tax Torpedo - How "Up to 85% Taxable" Actually Detonates
Nearly every article recites the same disclaimer: "Up to 85% of your Social Security benefits may be taxable." Then they move on, as if that sentence means anything actionable to a normal human being.
Here's the mechanism they skip:
The IRS taxes your Social Security based on something called Provisional Income (also called "Combined Income"):
Provisional Income = Adjusted Gross Income + Tax-Exempt Interest + 50% of your Social Security Benefit
These thresholds have never been adjusted for inflation since 1984. That means more retirees fall into the "85% taxable" bracket every single year - a slow-motion stealth tax increase nobody talks about.
The real danger: a Required Minimum Distribution (RMD) from a traditional 401(k) or IRA can spike your Provisional Income overnight, dragging Social Security income that was previously untaxed suddenly into the 85%-taxable zone.
This is the Tax Torpedo - a marginal tax rate on that extra dollar of income that can effectively exceed 40%, even if you're nowhere near the top tax bracket.
How to cover it in your projection:
Calculate your projected Provisional Income for each year of retirement, not just your gross income.
Flag any year where an RMD, pension start date, or part-time income pushes you past the $34,000 / $44,000 thresholds.
Model Roth conversions before you claim Social Security; ideally in the years between retirement and age 73 (RMD age) to shrink future taxable withdrawals and keep your Provisional Income low once benefits begin.
This single move, converting strategically before claiming, can save late-starters tens of thousands of dollars in unnecessary taxes over a 20-30 year retirement.
3. The Survivor's Cliff - The Income Drop Nobody Models
Standard retirement calculators assume both spouses live comfortably side-by-side until age 95, collecting two checks forever. Far too often, reality has other plans.
The Gap: When the first spouse dies, the survivor keeps only the higher of the two Social Security checks. The smaller check, sometimes worth $1,500–$2,500/month, disappears permanently.
At the exact same moment, the surviving spouse's tax filing status flips from Married Filing Jointly to Single, which cuts the standard deduction roughly in half and compresses every tax bracket.
The result is a devastating one-two punch: less income, taxed at a higher rate, often hitting at the worst possible time; when the survivor is older, potentially facing higher healthcare costs, and grieving.
How to model the Survivor's Cliff:
Pick a hypothetical year (or a realistic one, based on health/actuarial data) when the first spouse passes.
Remove the smaller Social Security check starting that year; permanently.
Re-run your tax calculation using Single filing status from that year forward.
Check whether the survivor's remaining income (smaller SS check gone, higher taxes) can still cover fixed expenses; housing, healthcare, insurance.
The fix most planners never suggest: if one spouse has a significantly smaller benefit, consider having the higher earner delay claiming until 70. This maximizes the check that survives; permanently protecting whichever spouse lives longest.
4. Bridging the Gap - Sequence of Returns Risk While You Wait to Claim
Every article parrots the same line: "Delay claiming until 70 and get a guaranteed 8% annual increase!" True. But not one of them explains how you're supposed to pay your mortgage, groceries, and health insurance premiums between age 62 and 70 while that 8% return is accruing on paper.
The Gap: To delay claiming, most retirees have to draw down their investment portfolio to cover living expenses.
If the market drops in those first few years of retirement, you're forced to sell assets at depressed prices to generate income, permanently damaging the portfolio's ability to recover.
This is Sequence of Returns Risk, and it's one of the most destructive and least discussed forces in retirement planning.
How to cover it? The Bridge Strategy:
Calculate the total income gap between retirement and age 70 (your annual expenses minus any pension, part-time income, etc.).
Multiply that annual gap by the number of years until you claim (e.g., $40,000/year × 8 years = $320,000).
Segregate that exact amount into safe, low-volatility assets - high-yield savings, short-term bonds, or a CD ladder; before you retire.
Spend from this "bridge bucket" first, leaving your equities untouched to recover and grow during any market downturn in those critical early years.
This turns "just delay until 70" from vague advice into an actual, fundable strategy - which is exactly the kind of specificity that separates a real plan from a calculator screenshot.
5. The COLA vs. Healthcare Inflation Disconnect
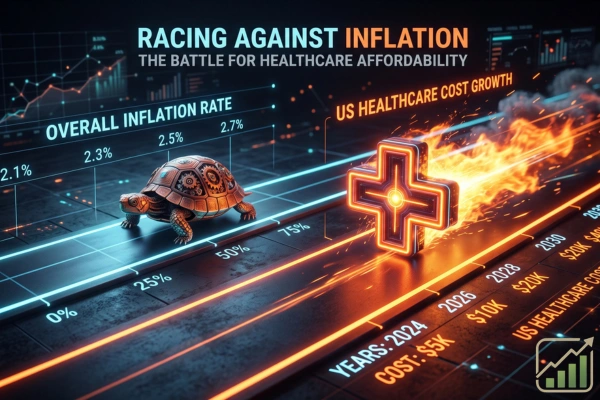
Mainstream projections tell you to assume a flat 2–3% Cost of Living Adjustment (COLA) on your Social Security income and call it done. That single assumption quietly wrecks long-term projections for millions of retirees.
The Gap: Social Security's COLA is pegged to the CPI-W (Consumer Price Index for Urban Wage Earners and Clerical Workers), an index weighted toward what working people buy: gas, groceries, transportation.
But retirees spend a disproportionate share of their budget on healthcare, which has historically inflated at 5-7% annually; more than double the CPI-W rate.
The result: your Social Security check grows at 2%, while your single largest retirement expense grows at 5-7%. That gap compounds brutally over a 20–30-year retirement.
How to cover it in your projection:
Use a split inflation model, not a single blended rate:
Social Security income growth: 2% annually (conservative COLA assumption)
General living expenses: 3% annually
Healthcare/medical expenses specifically: 5-7% annually
Re-run your 20-30 year projection with these three separate growth rates instead of one flat number.
Pay special attention to years after age 75, when healthcare typically becomes a larger share of total spending. This is where the disconnect does the most damage.
This single adjustment is the difference between a projection that looks fine on paper and one that survives an actual 30-year retirement.
Gap #6: The Medicare IRMAA Trap
Social Security calculators typically estimate your retirement benefit.
What they usually don't show you is how your retirement income can affect what you pay for Medicare.
Once you're enrolled in Medicare, higher income can trigger the Income-Related Monthly Adjustment Amount (IRMAA), which adds surcharges to your Medicare Part B and Part D premiums.
Here's the part that catches retirees off guard:
Medicare generally uses your modified adjusted gross income from two years earlier to determine whether you owe IRMAA.
That means a large Roth conversion, capital gain, retirement-account withdrawal, or other taxable-income event at age 63 could potentially increase your Medicare premiums at age 65.
Why This Matters
Imagine your Social Security calculator tells you that delaying benefits until age 70 will increase your monthly benefit.
That may be completely accurate.
But your Social Security claiming decision doesn't exist in isolation.
During the years before claiming Social Security, you might:
Perform Roth conversions
Withdraw money from traditional retirement accounts
Realize investment gains
Receive pension income
Generate business or other taxable income
Later face required minimum distributions (RMDs)
Those decisions can affect your modified adjusted gross income and potentially push you across an IRMAA threshold.
And IRMAA uses income brackets, which means crossing a threshold can increase Medicare premiums even if you only exceed the threshold by a relatively small amount.
The Real Question Isn't Just “When Should I Claim Social Security?”
A better retirement-planning question is:
How should Social Security, Medicare, Roth conversions, retirement withdrawals, taxes, and RMDs work together?
For some retirees, delaying Social Security may create a valuable planning window for Roth conversions or strategic withdrawals.
For others, aggressively generating taxable income during that window could create higher Medicare premiums later.
The goal isn't simply to avoid IRMAA at all costs.
Sometimes paying additional Medicare premiums may be worth it if a strategy produces larger long-term tax savings.
The important point is that the cost needs to be included in the decision.
What to Do Instead
Don't evaluate your Social Security claiming age using your projected benefit alone.
Model your retirement income year by year and include:
Social Security + pension income + retirement withdrawals + Roth conversions + investment income + taxes + Medicare premiums + future RMDs.
Then compare strategies based on their total long-term impact, rather than simply choosing the option that produces the largest Social Security check.
A Social Security calculator can tell you what your benefit might be.
A retirement plan needs to tell you how that benefit interacts with everything else.
Part 3: Putting It All Together - The Complete Projection Worksheet
Here's how the six variables combine into one real, defensible retirement projection:
If your plan holds up after all eight steps, you don't have a hopeful guess; you have a retirement projection that can actually survive retirement.
Our free tools can give you quick ideas and answers on a multitude of calculators. You can check them out on our financial tools page.
Get the Free Advanced Tools: Get More From Every Investment Decision
Unlock the free Execution Signals Tools Portal for advanced calculators, deeper risk analysis, and practical investor tools built to help you plan with numbers instead of guesses.
No credit card required.
Frequently Asked Questions
Do I need to include Social Security in my retirement number if I'm still years from claiming? Yes. Even a rough estimate materially changes how much you personally need to save. Ignoring it (or overestimating it) is one of the most common late-start retirement planning mistakes.
Is it better to claim at 62, at Full Retirement Age, or at 70? There's no universal answer. It depends on health, spousal benefits, the Survivor's Cliff, and whether you need a Bridge Strategy to delay safely. Generally, the higher-earning spouse benefits most from delaying to 70, since that becomes the surviving spouse's permanent check.
How much of my Social Security will actually be taxed? It depends entirely on your Provisional Income each year; which can change significantly due to RMDs, part-time work, or pension income. Model it year-by-year rather than assuming a flat percentage.
What if I'm a teacher or government employee? Does this all still apply? The core strategies still apply, but you must first run the WEP/GPO calculators at ssa.gov to get an accurate benefit number before doing anything else. Skipping this step means your entire projection is built on a fictional number.